Organizational complexity rarely arrives as an explicit strategic choice. More often, it accumulates one reasonable decision at a time.
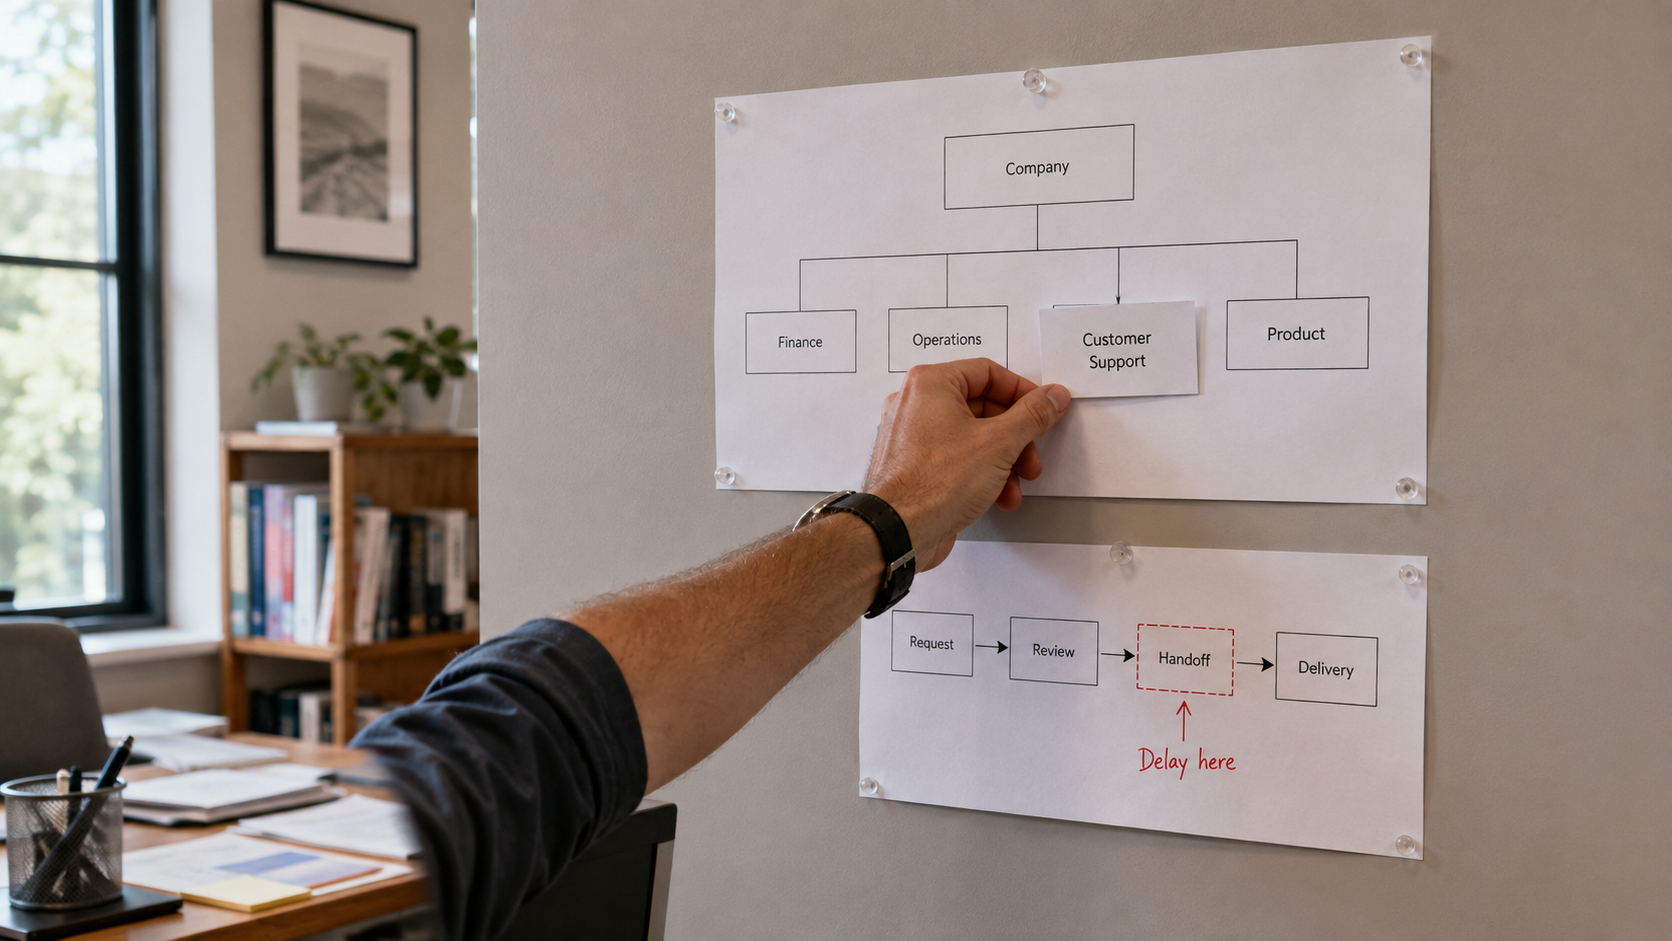
A new approval is introduced after a costly mistake. A governance committee is created to improve coordination. Another management layer is added because leaders need greater oversight. A specialist function is established as the organization grows. A new process is introduced to create consistency. Matrix relationships are added to connect capabilities that need to collaborate. Another recurring meeting appears because the existing structure does not reliably move information or decisions across organizational boundaries.
Individually, each decision may be entirely rational. Collectively, they can produce an organization that requires increasingly more effort simply to operate itself.
That effort represents a real organizational cost, but it rarely appears as a single line on a financial statement. Instead, the cost surfaces through slower decisions, additional meetings, repeated approvals, duplicated work, unnecessary escalation, managerial overload, unclear ownership, competing priorities, and employees spending more time navigating the organization than accomplishing the work the organization exists to perform.
Research in organizational design has long recognized that increasing differentiation, uncertainty, and interdependence require organizations to develop mechanisms for processing information and coordinating work. Galbraith's information-processing perspective, Thompson's work on organizational interdependence, and subsequent research on role ambiguity all reinforce a fundamental point: organizations need structures and mechanisms to manage complexity. Complexity itself, therefore, is not inherently evidence of poor design.
The more important question is whether the mechanisms created to manage legitimate business complexity continue to produce enough value to justify the capacity required to sustain them.
That leads to a question leaders should ask far more frequently:
Is the organizational capacity we are spending on complexity proportionate to the value that complexity creates?
The objective is not to make the organization as simple as possible. It is to distinguish complexity that enables performance from complexity that the organization continues paying for without receiving sufficient value in return.
Complexity Is Usually the Result of Reasonable Decisions
Few leadership teams intentionally design bureaucracy. Complexity typically develops because leaders are solving legitimate organizational problems.
As companies grow, specialization becomes necessary. Specialization creates interfaces. Interfaces require coordination. Coordination creates governance. Governance introduces meetings, processes, and decision requirements. New risks create controls. New products create roles. New markets create reporting relationships. Acquisitions introduce additional systems and practices.
Each response solves something, but each response also adds something.
The difficulty is that organizations tend to be better at adding mechanisms than removing them. A governance committee created during a transformation may continue meeting years after the transformation ends. An approval introduced after a single failure can become permanent. A reporting requirement established for a former executive may survive several leadership transitions. A management layer added during rapid growth may remain even after the nature of the work has changed.
Yesterday's solutions gradually become today's organizational infrastructure.
This creates an important asymmetry in organizational design. New complexity typically needs justification before it is introduced, but existing complexity is rarely required to continually demonstrate why it should remain.
Over time, organizations stop seeing individual processes, approvals, committees, reporting requirements, and layers as design choices. They become part of how the organization works.
That is how accumulated complexity becomes difficult to see.
Not All Complexity Is the Same
Attempts to simplify organizations often begin with an assumption that complexity itself is the problem. That can lead leaders to remove mechanisms that appear cumbersome without understanding why they exist or what value they provide.
A more useful diagnosis distinguishes among three forms of complexity.
Value-Creating Complexity
Some complexity originates in the business model itself. Multiple products, customer segments, geographies, regulatory environments, technologies, distribution channels, or specialized capabilities naturally increase the number of relationships the organization must manage.
A global enterprise operating across regulated markets should not expect to possess the same organizational simplicity as a small domestic company. Complexity in this context may be the necessary consequence of strategic choices that create significant value.
Enabling Complexity
Organizations introduce additional mechanisms to manage legitimate business complexity. Governance forums, specialist roles, risk controls, coordination mechanisms, planning processes, decision protocols, and management structures can all help the organization operate more effectively.
This complexity is not inherently wasteful. It exists because the underlying business requires integration, expertise, control, or coordination.
Accumulated Complexity
The third category is different. Accumulated complexity consists of organizational mechanisms whose original value has diminished, whose purpose has become unclear, or whose cost has grown disproportionate to the benefit they provide.
A process may have been necessary when it was created. A committee may once have resolved an important coordination problem. An approval may have addressed a genuine risk. A management layer may have provided critical integration during an earlier stage of growth.
The issue is not whether the mechanism was originally justified. It is whether it remains justified now.
That distinction is critical because the solution to organizational complexity is not indiscriminate simplification. Leaders need to protect complexity that creates or enables value while identifying complexity the organization has simply accumulated.
Complexity can become difficult to diagnose because the business creates legitimate complexity, the organization creates mechanisms to manage it, and those mechanisms accumulate over time. Eventually, leaders experience the consequences as organizational friction without necessarily tracing that friction back to the design decisions that created it.
The Hidden Cost Is Organizational Capacity
The visible costs of complexity are relatively easy to identify. Additional management layers create compensation expense. More systems require technology investment. Larger corporate functions require headcount. Governance processes require administrative support.
The more consequential costs are often less visible because they consume organizational capacity rather than appearing as direct expenses.
Consider a recurring governance meeting involving fifteen senior leaders for ninety minutes every week. The visible consumption is twenty-two and a half leadership hours. The actual capacity requirement is larger. Employees prepare materials before the meeting, leaders review them, actions are coordinated afterward, and decisions may wait until the forum convenes. Other work is displaced because leadership attention is finite.
An unnecessary approval creates a similar effect. Its cost is not limited to the minutes required to approve something. The approval may increase decision latency, require preparation, create follow-up, introduce another handoff, and encourage employees to wait rather than act.
An additional management layer does more than increase payroll. It changes the distance between decisions and the work, adds another communication interface, and potentially increases the number of people through whom information must travel.
The hidden cost of complexity is therefore not simply money. It is the portion of the organization's finite capacity required to navigate itself.
Capacity Leakage
As complexity accumulates, organizations can experience what TQG describes as capacity leakage, the gradual diversion of time, attention, leadership energy, and talent away from value-creating work and toward navigating the organization itself.
Capacity leakage appears through additional coordination, repeated approvals, unnecessary escalation, duplicate work, excessive preparation, recurring reconciliation, unclear ownership, and the informal effort employees expend determining how to move work forward. No individual activity may appear especially damaging. The cost becomes significant through accumulation.
This is one reason complexity can remain invisible in conventional productivity measures. Employees continue producing results, but they expend increasingly more effort overcoming organizational friction to do so.
A capable employee may know which informal relationship can accelerate an approval. An experienced manager may understand how to navigate overlapping governance processes. A senior leader may personally resolve disagreements that formal decision structures fail to settle.
The organization still produces an outcome. What the outcome does not reveal is how much organizational capacity was required to produce it.
That distinction matters because an organization can maintain acceptable performance while simultaneously becoming less efficient at producing that performance.
Complexity Often Hides Inside Strong Performance
Capable people are remarkably effective at compensating for poorly designed systems.
When decision ownership is unclear, experienced employees use relationships to obtain decisions. When processes are cumbersome, teams develop workarounds. When organizational boundaries create friction, strong managers personally coordinate across them. When governance is slow, influential leaders find ways to accelerate critical issues.
These behaviors can preserve organizational performance for surprisingly long periods. They can also hide the underlying problem.
Leaders observe acceptable results and reasonably conclude that the organization is functioning. What they may not see is the extraordinary amount of individual effort required to compensate for the system.
This helps explain why complexity often becomes visible during periods of growth, leadership transition, acquisition, restructuring, or significant strategic change. The organization may not have suddenly become poorly designed. The people and informal mechanisms that previously absorbed its complexity may simply have reached their limits.
What appears to be a sudden execution problem can therefore be accumulated organizational friction finally exceeding the organization's ability to compensate for it.
This is also why heroic performance deserves careful interpretation. An employee who repeatedly saves an initiative, resolves cross-functional conflict, or personally navigates an inefficient process may be exceptionally capable. They may also be revealing a system that depends too heavily on exceptional people to function.
Complexity Multiplies at the Interfaces
Some of the most consequential organizational complexity does not reside within individual functions or systems. It exists between them.
A finance process may be entirely rational when examined from Finance's perspective. HR may have a defensible talent process. Operations may have sensible governance. Technology may have appropriate controls. Sales may have logical approval requirements.
Employees experience the intersections.
A decision crossing several functions may encounter multiple information requirements, different priorities, overlapping approvals, competing systems, and unclear ownership. Each individual requirement may be reasonable, yet the combined experience can become extraordinarily complex.
This creates an important organizational design principle:
Complexity often resides less within organizational systems than in the relationships between them.
That is why optimizing individual functions does not necessarily optimize the organization. A process improvement within one function can even transfer complexity somewhere else if the broader workflow is not considered.
As organizations become increasingly matrixed and interdependent, these interfaces matter more. Adding another function, governance body, specialist role, or matrix relationship does not create only one new organizational element. It creates new relationships with the elements already present.
Complexity can therefore grow faster than the organization expects because the number of interactions expands alongside the number of components.
Decision Complexity Is Especially Expensive
Decision-making is one of the clearest places where accumulated complexity becomes visible.
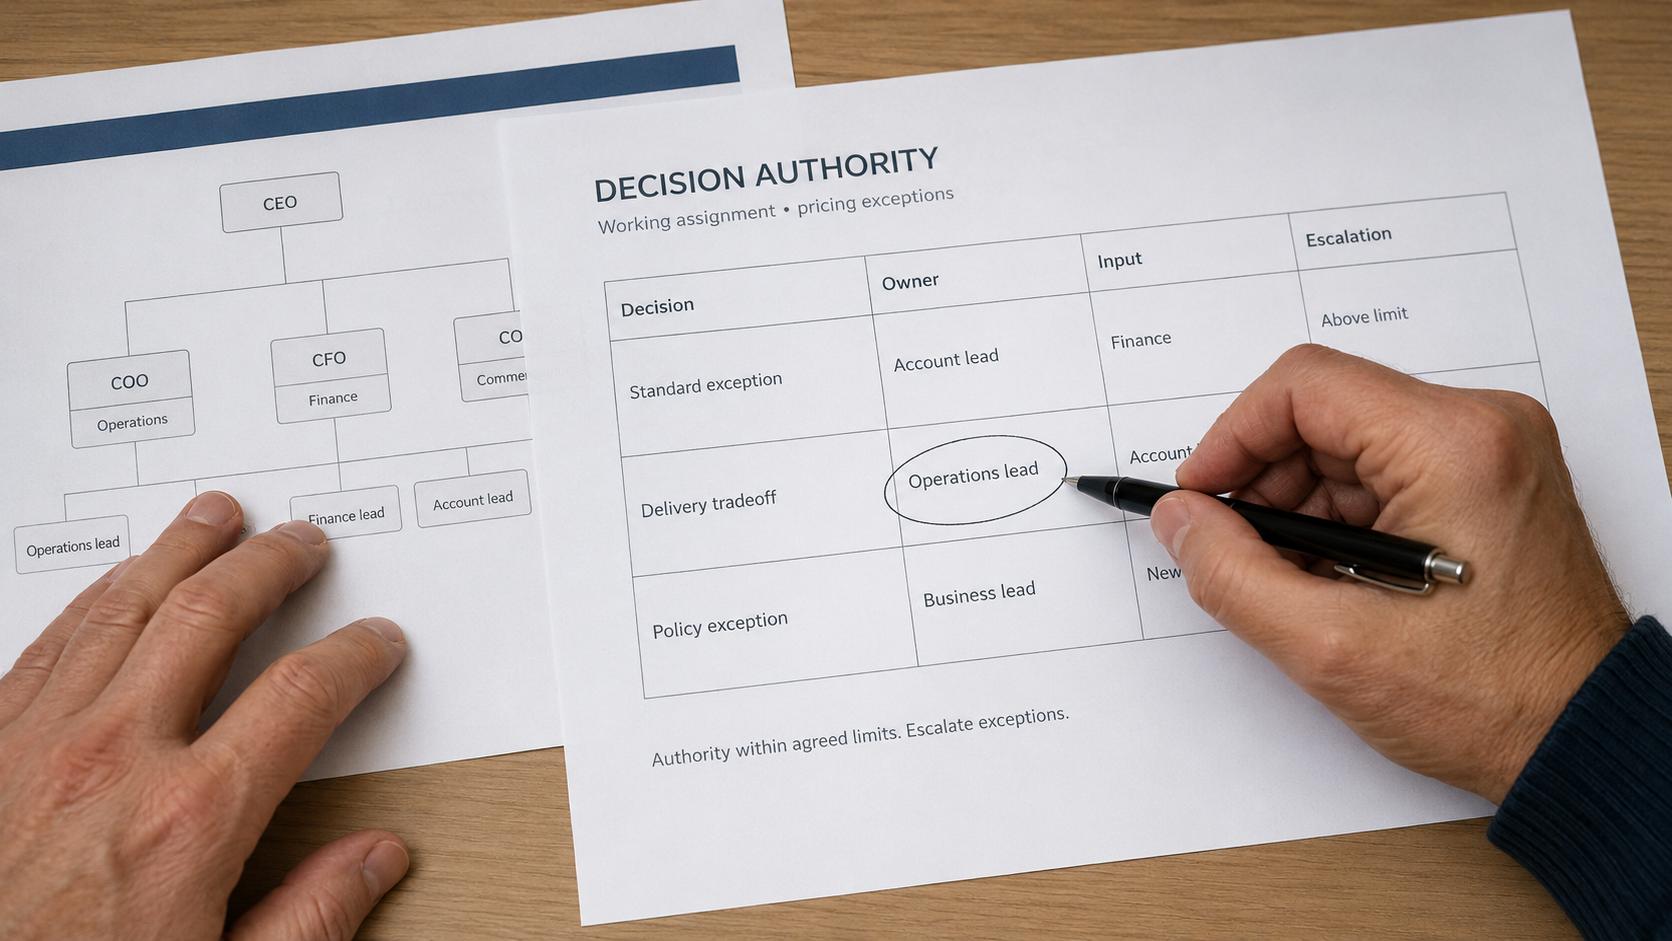
As organizations grow, more functions acquire legitimate interests in important decisions. Specialists provide expertise, corporate functions manage risk, business units represent operating realities, and leaders seek appropriate visibility. The result can be a large number of people involved in a decision without corresponding clarity about who actually owns it.
Organizations then begin confusing participation with authority.
More stakeholders provide input, more leaders expect consultation, and more functions acquire informal veto power. Decisions move into governance forums because the normal operating structure cannot resolve them. Escalation becomes routine because accountability for the final choice is unclear.
The decision becomes organizationally expensive even when no individual approval appears unreasonable.
Research and practice surrounding decision roles reinforce why this matters. Organizations need mechanisms for incorporating appropriate expertise and managing risk, but those mechanisms become costly when decision authority is ambiguous.
Complexity reduction therefore requires more than removing steps. Leaders need to determine which perspectives genuinely improve a decision, which controls manage meaningful risk, who needs to be informed, and where authority ultimately resides.
Otherwise, eliminating one meeting may simply move the same unresolved decision into another forum.
The Wrong Objective Is Simplicity
Once leaders recognize the cost of complexity, the natural response is simplification. That can create another problem.
Some organizational complexity produces significant value. Regulatory controls may prevent catastrophic risk. Specialized expertise may materially improve decision quality. Global coordination mechanisms may allow the organization to serve customers consistently across markets. Additional review may protect employees, customers, shareholders, or the organization itself from consequential errors.
Removing these mechanisms solely because they add steps would make the organization simpler while potentially making it worse.
The appropriate objective is therefore not minimum complexity. It is justified complexity.
This requires leaders to stop treating simplicity as an end state and instead evaluate the relationship between the capacity complexity consumes and the value it creates.
That relationship is the foundation of the TQG Complexity Value Test.
The TQG Complexity Value Test
Every significant layer of structure, governance, process, coordination, approval, reporting, or control requires organizational capacity to sustain it. TQG's Complexity Value Test asks leaders to evaluate that complexity against two fundamental questions:
How much organizational capacity does this complexity consume?
How much organizational value does it create?
Value may come through improved decision quality, risk reduction, specialization, consistency, customer outcomes, strategic alignment, scalability, capability, or another outcome the organization legitimately needs.
Capacity cost may appear through leadership time, coordination requirements, decision delays, handoffs, meetings, process steps, cognitive burden, escalation, rework, or talent diverted from more valuable work.
The purpose of the test is not to manufacture mathematical precision where it does not yet exist. The relationship between different forms of organizational capacity and different forms of value requires careful evidence, context, and judgment.
Instead, the test creates a disciplined leadership question. Rather than asking whether something is complex, leaders ask whether its complexity is worth what the organization spends sustaining it.
Viewed together, organizational value and capacity cost create four useful categories for evaluating complexity: Efficient Complexity, Strategic Complexity, Incidental Complexity, and Destructive Complexity.
Efficient Complexity creates meaningful organizational value without consuming disproportionate capacity. A specialist review that materially improves decision quality without creating significant delay may fall into this category. This complexity should generally be preserved and periodically reassessed.
Strategic Complexity consumes substantial organizational capacity but creates correspondingly important value. Regulatory governance, sophisticated risk controls, critical quality processes, or coordination across strategically important global operations may belong here. The objective should not necessarily be removal. Leaders should protect the value while continually looking for ways to reduce the operating burden.
Incidental Complexity creates relatively little value but also consumes relatively little capacity. It may not warrant immediate executive attention, but it becomes a reasonable candidate for simplification when related processes or structures are redesigned.
Destructive Complexity consumes substantial organizational capacity while producing insufficient corresponding value. Redundant approvals, overlapping governance, duplicate reporting, unnecessary layers, unclear decision ownership, and recurring meetings created to compensate for poor integration may fall into this category. This is where redesign can release meaningful organizational capacity.
This framework deliberately reframes the simplification conversation. The question is no longer simply what can be removed. It becomes what should be protected, what should be optimized, and what should no longer exist in its current form.
Complexity Should Have to Earn Its Cost
Organizations usually scrutinize complexity when it is introduced. Leaders discuss why a new committee is necessary, why another approval should exist, why a management layer should be added, or why a process needs additional controls.
Once established, those mechanisms rarely face the same burden of proof.
The organization continues paying for them through time, attention, coordination, and cognitive load even as strategy, technology, leadership, workforce capability, and business conditions change.
This suggests that complexity should be treated more like an investment portfolio than permanent organizational infrastructure. Some investments continue producing value and deserve to remain. Others need to be redesigned. Some no longer solve a problem worth the capacity they consume.
The discipline is not merely to ask whether complexity was justified when it was created. It is to ask whether complexity continues to earn its cost.
The Real Cost Includes Opportunity Cost
Capacity consumed by complexity has another dimension that is easy to overlook.
Every hour spent navigating internal complexity is an hour that cannot be used somewhere else.
If twenty executives spend two hours each month in a governance meeting, the visible requirement is forty executive hours. But the economic and organizational cost is not limited to those hours. Those leaders could have spent the same capacity with customers, developing leaders, solving strategic problems, accelerating another decision, evaluating emerging risks, or building future capability.
Organizational capacity is finite. Every internal requirement therefore competes with another potential use of that capacity.
This makes opportunity cost particularly important at senior levels because leadership attention is one of the organization's scarcest resources. An organization that requires executives to spend disproportionate time resolving internal coordination problems is effectively allocating strategic capacity toward maintaining its own complexity.
The expense may never appear directly on a financial statement. The organization still pays it.
Organizations Need a Discipline of Subtraction
Most organizational design occurs through addition.
When coordination fails, organizations add meetings. When a risk emerges, they add controls. When leadership needs visibility, they add reporting. When accountability is unclear, they add governance. When capability is missing, they add roles. When a process fails, they add another step intended to prevent the failure from recurring.
The logic behind each addition may be reasonable. The problem is that organizations rarely develop an equally disciplined process for subtraction.
Processes do not automatically disappear when the underlying problem changes. Committees do not dissolve when their original purpose has been fulfilled. Reporting requirements do not expire when leadership needs change. Layers do not remove themselves when the work becomes simpler.
This means organizations can continue accumulating yesterday's solutions while introducing tomorrow's.
Strong organizations need a discipline of subtraction equal to their discipline of addition. That does not mean periodically cutting processes or headcount to demonstrate simplification. It means deliberately revisiting organizational mechanisms and asking whether the conditions that justified them still exist, whether the mechanism still creates sufficient value, and whether the same outcome could now be achieved with less capacity.
Subtraction should be an organizational design capability, not an occasional cost-reduction exercise.
Diagnosing Complexity Before Removing It
A disciplined complexity assessment begins by identifying where organizational capacity appears to be consumed disproportionately.
Recurring decision delays, excessive escalation, meeting load, duplicate work, repeated approvals, overlapping roles, unnecessary handoffs, management time, process steps, and employee workarounds can all provide useful evidence. Qualitative evidence matters as well because employees frequently know exactly where friction exists even when the organization has never quantified it.
Once those areas are visible, the next question should not automatically be what can be removed. Leaders need to understand why the complexity exists and what value it is intended to create.
Some complexity will prove necessary. Some will reveal opportunities for optimization. Some will exist because another organizational system is failing. A meeting may compensate for unclear decision rights. Additional reporting may compensate for poor information flow. Another management layer may compensate for weak role clarity or capability.
Other complexity will have no compelling explanation beyond organizational habit.
That category deserves particular attention.
The purpose of diagnosis is to distinguish complexity that enables the organization from complexity the organization has simply learned to tolerate.
What Great Organizations Do Differently
Organizations that manage complexity effectively do not pursue simplicity as an abstract virtue. They recognize that growth, specialization, risk, scale, and interdependence naturally create complexity, but they remain disciplined about the capacity required to sustain it.
They examine complexity at the interfaces between functions rather than evaluating organizational units only in isolation. They clarify decision authority so meetings and escalation do not become substitutes for ownership. They periodically challenge governance mechanisms, reporting requirements, approvals, processes, and management layers instead of assuming that mechanisms created under previous conditions remain necessary indefinitely.
They also treat workarounds as organizational evidence. When experienced employees routinely bypass formal processes, when senior leaders repeatedly intervene to accelerate decisions, or when particular individuals become indispensable because they understand how to navigate the organization, those patterns are not celebrated without examination. Leaders ask what those individuals are compensating for.
Most importantly, these organizations distinguish between complexity that creates value, complexity necessary to enable that value, and complexity that has accumulated without sufficient purpose. They protect the first, optimize the second, and challenge the third.
That makes simplification more strategic. The objective is not fewer meetings, fewer processes, fewer controls, or fewer layers for their own sake. It is to release organizational capacity without destroying organizational value.
1. Where does our organization require disproportionate effort simply to get work done?
Recurring escalation, coordination, approvals, meetings, rework, and informal workarounds can reveal where complexity is consuming capacity.
2. Which organizational mechanisms exist because they still create value, and which exist primarily because they have always existed?
Every recurring governance process, reporting requirement, approval, committee, and management layer should have a defensible current purpose.
3. Where are high performers or senior leaders compensating for organizational complexity?
Heroic execution can conceal system problems by allowing the organization to perform despite unnecessary friction.
4. Which elements of our current complexity would we deliberately rebuild if we were designing the organization today?
This question helps distinguish strategically necessary complexity from mechanisms inherited from conditions that no longer exist.
5. Is the organizational capacity we are spending on complexity proportionate to the value that complexity creates?
Complexity that produces significant value may deserve to remain. Complexity that consumes substantial capacity without corresponding value should become a candidate for redesign.
Together, these questions move the leadership conversation away from whether the organization simply feels bureaucratic and toward a more useful diagnosis of where complexity exists, why it exists, what it costs, and whether it continues to create sufficient value.
Complexity is not inherently evidence of poor organizational design. Some complexity is the unavoidable, and sometimes valuable, consequence of scale, specialization, risk management, geographic reach, product diversity, and interdependent work.
The problem is complexity that no longer earns the organizational capacity required to sustain it.
Organizations rarely experience that cost all at once. It accumulates through another approval, another governance mechanism, another reporting requirement, another interface, another management layer, and another meeting created to coordinate the mechanisms already in place. Capable employees and strong leaders compensate, sometimes for years, until the accumulated friction becomes too large to absorb.
That is why the objective should not be organizational simplicity for its own sake. It should be organizational intentionality. Every significant element of complexity should exist because the value it creates justifies the capacity it consumes. When that relationship changes, leaders should be willing to redesign or remove it.
The principle is straightforward:
Complexity is not inherently a problem. Unproductive complexity is. Every layer of complexity should earn the organizational capacity required to sustain it.
Organizations that understand this do more than simplify. They reclaim capacity and redirect it toward customers, decisions, innovation, leadership, capability, and execution.
That is the real opportunity hidden inside organizational complexity.
Supporting Research
- Galbraith, J. R. (1974). Organization design: An information processing view. Interfaces, 4(3), 28–36.
- March, J. G., & Simon, H. A. (1958). Organizations. Wiley.
- Thompson, J. D. (1967). Organizations in action: Social science bases of administrative theory. McGraw-Hill.
- Tubre, T. C., & Collins, J. M. (2000). Jackson and Schuler (1985) revisited: A meta-analysis of the relationships between role ambiguity, role conflict, and job performance. Journal of Management, 26(1), 155–169.